No credit impact
See what the deal can carry through a soft pull that leaves your personal and business credit untouched.
Tell us about the deal — not about a company you don't own yet. We match you with lenders who fund acquisitions, then hand you off to a secure application when you're ready.
These are the numbers a lender runs the deal on.
Seller's Discretionary Earnings. A lender sizes the loan off this number.
A recent ownership change is underwritten differently.
Lenders generally want the lease term plus options to cover at least 10 years.
The buyer is underwritten separately from the business. This is your half — we already have your name and how to reach you.
Lenders underwrite the business you're buying, not a projection. These are the two things they always ask for.
Attach what you have. Nothing here holds up your pre-qualification — you can add the rest later in your secure application.
The CIM, the LOI, bank statements, equipment lists, licences — anything else you already have on the business you're buying. No limit on how many.
PDF, JPG, PNG, Excel or Word, up to 100 MB per file. Bank statements, a personal financial statement and a debt schedule come later in the secure application.
Check the numbers. You can go back and change anything.
Next you'll finish in the secure application, where identity and credit verification happen.
One application, checked against the lenders who actually write SBA 7(a) and conventional acquisition loans — so you can spend your time on diligence instead of chasing banks.
See what the deal can carry through a soft pull that leaves your personal and business credit untouched.
Describe the deal once and compare SBA and conventional structures from multiple lending partners in one place.
Seller notes, standby debt and earnouts are part of the structure here, not an exception the lender has to be talked into.
Same as a Bizbe deal: you can see every step and exactly what it needs from you.
One application on the deal, with no fee and no obligation.
The deal is evaluated against lenders who underwrite acquisitions at this size.
Review real terms — rate, amortization, injection and guaranty — side by side.
Your lender funds to escrow and closing alongside your cash and the seller note.
Walk in as the owner, with working capital already in place for the transition.
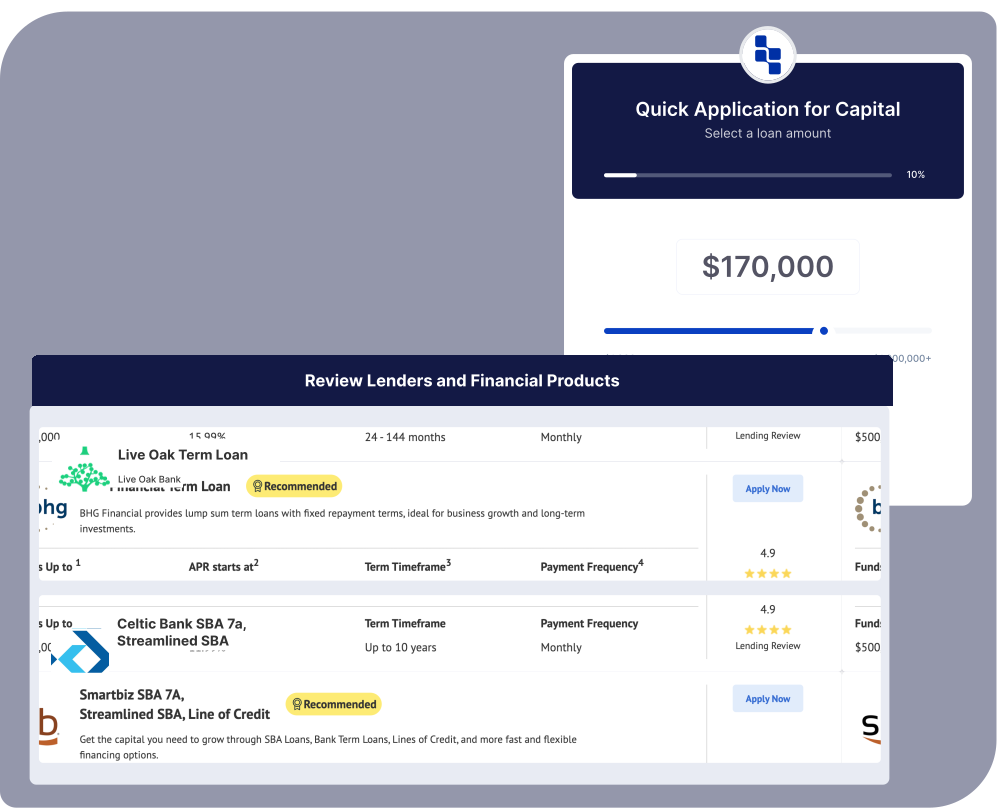
Options that match how a Main Street acquisition actually runs — from LOI to the closing table.
Compare rates, terms and injection requirements so your cash goes as far as it can.
Know where you stand early, so diligence and your lender's underwriting run in parallel instead of in sequence.
Lenders who know the program — the 10% injection, standby seller notes, and the full-time owner rule.
Bring real numbers to the LOI. Apply on the deal, compare your options, and negotiate knowing what a lender will actually fund.